
Author: Competition Subaru of Smithtown Team
As you consider purchasing a Subaru, whether it’s for navigating the tree-lined streets of Saint James or heading to Deepwells Farm for a family outing, understanding the financing options available is essential. At Competition Subaru of Smithtown, we recognize that choosing between financing and leasing can impact your local driving experience, especially with the varied Long Island weather. Financing offers the benefit of ownership, providing flexibility for family trips to Caleb Smith Preserve or carrying outdoor gear for adventures along the Nissequogue River, while leasing may provide lower monthly payments for those who prefer to drive a new vehicle every few years.
With over a decade of service in the community, Competition Subaru of Smithtown has built a reputation for expertise in maintaining Subaru vehicles, ensuring that local drivers in Smithtown, Holbrook, South Setauket, and Ronkonkoma receive trusted guidance and support for their automotive needs.
Key Takeaways (TL; DR)
- Your Credit Score Matters: A strong credit score significantly influences your financing options, affecting the interest rates and terms you may qualify for. Higher scores can lead to lower costs over the life of your loan.
- Subaru Financing Options: Subaru offers various financing solutions that can streamline your purchasing process, often allowing for pre-approval before visiting the dealership, which saves time and effort.
- Understanding Financing vs. Leasing: Financing allows you to own your Subaru, building equity over time, while leasing typically offers lower monthly payments but doesn’t build ownership.
- Flexible Lease-End Choices: At the end of your lease, you can choose to purchase the vehicle, lease a new one, or return it, providing options that fit your changing needs.
- Special Programs for Savings: Subaru offers programs for recent graduates, military personnel, and loyalty rewards that can help reduce your overall financing costs.
- Be Prepared: Collect necessary documents, check your credit, and establish a budget before beginning the financing process to make your experience smoother and more efficient.
Understanding Automotive Financing for Subaru Buyers
Automotive financing is a common way to purchase a Subaru, allowing you to take out a loan from Subaru Motors Finance (SMF) or a local bank to cover your vehicle's cost. You'll repay this loan through monthly payments over a fixed period, known as the loan term. This arrangement helps you gradually work towards owning your Subaru, whether it's a reliable Outback for family trips to Deepwells Farm or a versatile Crosstrek for weekend adventures.
As you make each payment, you build equity, which is essentially the portion of the car you own. When the last payment is made, you receive the vehicle's title, and it's yours without any obligations. This is particularly beneficial for Saint James drivers who appreciate customizing their vehicle for local driving conditions, like navigating the tree-lined streets of Lake Avenue or heading out for hikes at Caleb Smith State Park.
Understanding Subaru Financial Services

Subaru Motors Finance (SMF) is the designated financial partner for Subaru, aimed at providing customers with a seamless and convenient way to finance their vehicles. This service is designed to offer competitive rates and tailored programs specifically for Subaru buyers.
At dealerships like Competition Subaru of Smithtown, you can initiate your financing journey right here or even apply for online pre-approval from the comfort of your home. Keep in mind that offers vary based on credit history and financial qualifications.
SMF evaluates your application, taking into account factors like your credit score and income, to determine your eligibility for loans or leases. This connection to the Subaru family often provides access to exclusive offers, such as special interest rates or loyalty incentives that enhance your buying experience.
What Does It Mean to Lease a Subaru?
Leasing a Subaru means you’re essentially entering a long-term rental agreement. Instead of paying for the full price of the vehicle, you pay to use it for a predetermined period, typically between 24 and 36 months. Your monthly payment is influenced by the car's depreciation, which is the difference between its original value and its estimated worth at the end of your lease, termed the residual value. Additionally, you’ll pay interest, known as the money factor, along with any applicable fees.
Understanding these concepts is crucial for Saint James drivers. For instance, if you choose a Subaru Forester, its residual value can affect your monthly payments significantly. Typically, leasing results in lower monthly costs compared to financing a purchase, making it an appealing option for those who prefer the latest technology and safety features every few years. This can be particularly beneficial for residents who frequently navigate the scenic routes around Caleb Smith State Park or commute along North Country Road.
What Are My Options When My Subaru Lease Ends?
As your Subaru lease term approaches its end, you have several flexible options to consider for your next steps.
- Purchase Your Leased Subaru: You can buy your vehicle at the residual value specified in your lease agreement, which can be a great way to keep a car you already love.
- Lease or Buy a New Subaru: If you're ready for something new, you can return your current vehicle and start a new lease or purchase agreement, exploring models like the versatile Subaru Outback or the rugged Crosstrek.
- Return Your Vehicle: Schedule an inspection to assess its condition and address any excess wear or mileage before handing it back, ensuring a smooth transition.
Understanding the Differences Between Financing and Leasing
When it comes to getting a new Subaru, financing and leasing are two popular options that cater to different needs. Here’s a breakdown of how they compare, helping you make the best choice for your lifestyle in Saint James.
The fundamental distinction between financing and leasing revolves around vehicle ownership. Financing leads to ownership, while leasing involves paying for the use of the vehicle for a specified period.
| Feature | Financing a Subaru | Leasing a Subaru |
|---|---|---|
| Ownership | Title transfers to you after the final payment. | Vehicle remains with the leasing company. |
| Monthly Payments | Generally higher; based on the full value of the vehicle. | Lower payments; based on expected depreciation. |
| Upfront Costs | Down payment is often recommended. | First payment and acquisition fees are common. |
| Customization | You can modify the vehicle as you wish. | Must return the vehicle in its original condition. |
| Mileage | No mileage restrictions apply. | Annual mileage caps apply, with fees for exceeding limits. |
| Wear & Tear | Excessive wear can lower resale value. | Potential fees for excess wear at lease end. |
| End of Term | You can keep, sell, or trade the vehicle. | Options to return, buyout, or lease a new vehicle. |
What Factors Determine My Financing or Lease Terms?
When considering financing or leasing a Subaru from Competition Subaru of Smithtown, several key factors come into play that can significantly affect the terms you receive.
- Credit Score: A higher credit score typically translates to lower interest rates, making your financing more affordable.
- Down Payment: A substantial down payment can decrease your monthly payments and reduce overall interest paid over the life of the loan.
- Term Length: Opting for a longer term may lower your monthly payment, but it could increase the total interest cost.
- Vehicle Price/Type: The price and type of Subaru you choose can influence available promotions, which may provide a better deal.
- Debt-to-Income Ratio (DTI): Lenders evaluate your DTI to determine your capacity to make payments comfortably, affecting the terms they offer.
What Special Programs Does Subaru Offer?
Subaru provides various special programs designed to assist qualified buyers, making it easier for them to get behind the wheel of a new vehicle.
- Subaru College Graduate Program: Offers incentives for recent graduates who can provide proof of graduation and employment.
- Subaru Military Appreciation Offer: Provides benefits for eligible U.S. military personnel and their spouses.
- Loyalty Benefits: Rewards current Subaru owners with savings on select new models.
- Local and Regional Promotions: Unique offers that vary by region and dealer, adapting to local market conditions.
How to Apply for Subaru Financing or a Lease

Starting your application online is simple and can be completed at our dealership.
- Get Pre-Qualified: Assess potential terms without impacting your credit score.
- Gather Documents: Prepare your driver's license, proof of income, residence verification, and insurance details.
- Complete Application: A full credit check is necessary (hard inquiry).
- Review & Sign: Verify your annual percentage rate (APR), loan term, payment amount, and any additional protections.
Paying Cash vs. Financing: What’s the Best Option for You?
Opting to pay cash means immediate ownership of your Subaru, free from interest payments. However, this choice can deplete your savings, potentially leaving you without a financial cushion for emergencies or unexpected expenses.
On the other hand, financing allows you to keep your savings intact while spreading the cost of your Subaru over time. This approach can provide flexibility in your budget, but it also means committing to monthly payments. Ultimately, your decision should consider your financial situation and comfort level with managing ongoing expenses.
What Are the Pros and Cons of Each Payment Method?
Explore the benefits and drawbacks of financing versus leasing a Subaru to determine which option best suits your driving needs and lifestyle in Saint James.
Pros of Financing a Subaru
- You Own It: After the final payment, the Subaru is yours to keep, sell, or trade as you wish.
- No Mileage Penalties: Enjoy unlimited driving without worrying about exceeding a mileage cap.
- Freedom to Personalize: Modify or accessorize your Subaru to reflect your unique style.
- Build Equity: Each payment increases your ownership stake, which can be beneficial when selling or trading.
- Long-Term Savings: Owning your vehicle long-term can lead to significant savings compared to leasing.
Cons of Financing a Subaru
- Higher Monthly Payments: Typically, financing costs more per month than leasing.
- Maintenance Costs: After the warranty expires, you’re responsible for all repair costs.
- Depreciation: The vehicle's value decreases over time, which can affect resale value.
- Initial Investment: Financing might require a larger down payment than leasing.
Pros of Leasing a Subaru
- Lower Monthly Payments: Lease payments are generally lower since you’re paying for depreciation, not the full price.
- Access to Newer Vehicles: Leasing allows you to drive the latest Subaru models with advanced features more often.
- Fewer Repair Costs: Most leases cover the warranty period, reducing your out-of-pocket expenses.
- Easy Turn-In: At the end of your lease, simply return the vehicle—no hassle with resale.
- Tax Benefits: In some cases, leasing may offer tax advantages depending on your situation.
Cons of Leasing a Subaru
- No Ownership: You don’t build equity in the vehicle, which can be a downside for long-term planning.
- Mileage Limits: Exceeding the agreed mileage can result in costly per-mile fees.
- Wear and Tear Fees: You may face charges for excessive wear and tear upon return.
- No Customization: You must keep the vehicle in its original condition, limiting personalization options.
What Are Some Practical Tips for Getting the Best Deal?

For drivers around Saint James, being prepared and strategic can significantly lower your vehicle costs. Here are some actionable tips to consider when you're in the market for a Subaru.
- Check Your Credit Score: Address any discrepancies before applying to improve your chances of securing better financing rates.
- Shop Around for Rates: Obtain quotes from both your bank or credit union and the dealership to compare financing options.
- Purchase Timing Matters: Look for deals at the end of the month or during model-year transitions, when dealerships often offer incentives.
- Negotiate the Vehicle Price First: Focus on the price of the Subaru separately from financing terms to maximize your savings.
- Know the Key Numbers: Familiarize yourself with essential figures like cap cost, residual value, and money factor for leases, or APR and total financed amount for loans.
Frequently Asked Questions (FAQs)
What should I expect during the finance process?
During the finance process at Competition Subaru of Smithtown, our team will guide you through the necessary paperwork and explain financing options tailored to your needs, ensuring a smooth experience.
How can I prepare for potential upselling in the finance office?
Competition Subaru of Smithtown's finance team will clearly outline available options, allowing you to consider any additional services or products that may enhance your vehicle ownership experience.
What are common complaints about the finance team at Competition Subaru of Smithtown?
Instead of focusing on complaints, many customers appreciate how Competition Subaru of Smithtown's finance team prioritizes transparency and communication, helping to address any concerns and foster trust.
How can I ensure transparency in my financing agreement?
To ensure transparency, Competition Subaru of Smithtown will review your financing agreement with you, clarifying all terms and fees so that you fully understand your commitment.
What community initiatives does Competition Subaru of Smithtown support?
Competition Subaru of Smithtown actively participates in the Subaru Love Promise initiative, supporting local organizations like the Smithtown Children’s Foundation and Stony Brook Children’s Hospital, demonstrating our commitment to the community.
How does Competition Subaru of Smithtown ensure a stress-free dealership experience?
The team at Competition Subaru of Smithtown is dedicated to providing a hassle-free experience by treating every customer like a neighbor and leveraging decades of automotive expertise to assist with all your needs.
About Competition Subaru of Smithtown
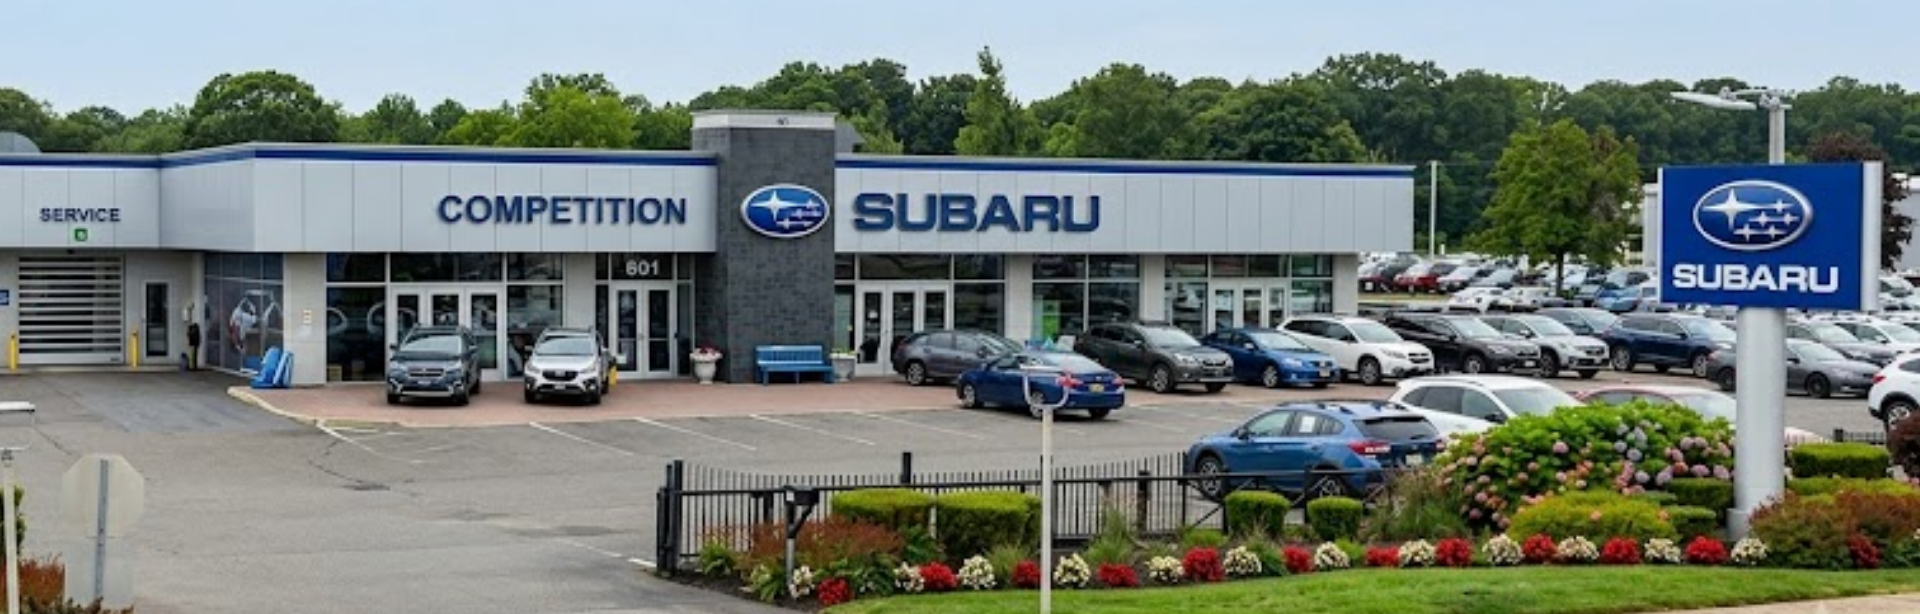
As the team at Competition Subaru of Smithtown, we are proud to serve drivers across St. James, Smithtown, and the broader Long Island, New York community. Backed by the legacy of the Competition Automotive Group—founded in 1962 by championship race car driver Joseph C. Buzzetta—our family-owned dealership brings decades of trusted automotive expertise to every driver who walks through our doors. Beyond helping you find or service the perfect vehicle, we demonstrate our commitment to excellence through active participation in the Subaru Love Promise initiative and by giving back locally to organizations like the Smithtown Children’s Foundation, Stony Brook Children’s Hospital, and Paws of War. From our state-of-the-art facility equipped with factory-trained technicians to our deeply rooted family values, we treat every customer like a neighbor. Whether you need a new vehicle or expert maintenance, our dedicated team is here to deliver an unmatched, stress-free dealership experience built on integrity and decades of passion.